Business & Growth
Roof Replacement Cost: An Expert’s Financial Breakdown
Understanding the true roof replacement cost is crucial for any homeowner. This guide breaks down average prices, material variations, labor expenses, and hidden factors for 2026, empowering you to make informed financial decisions for your home.

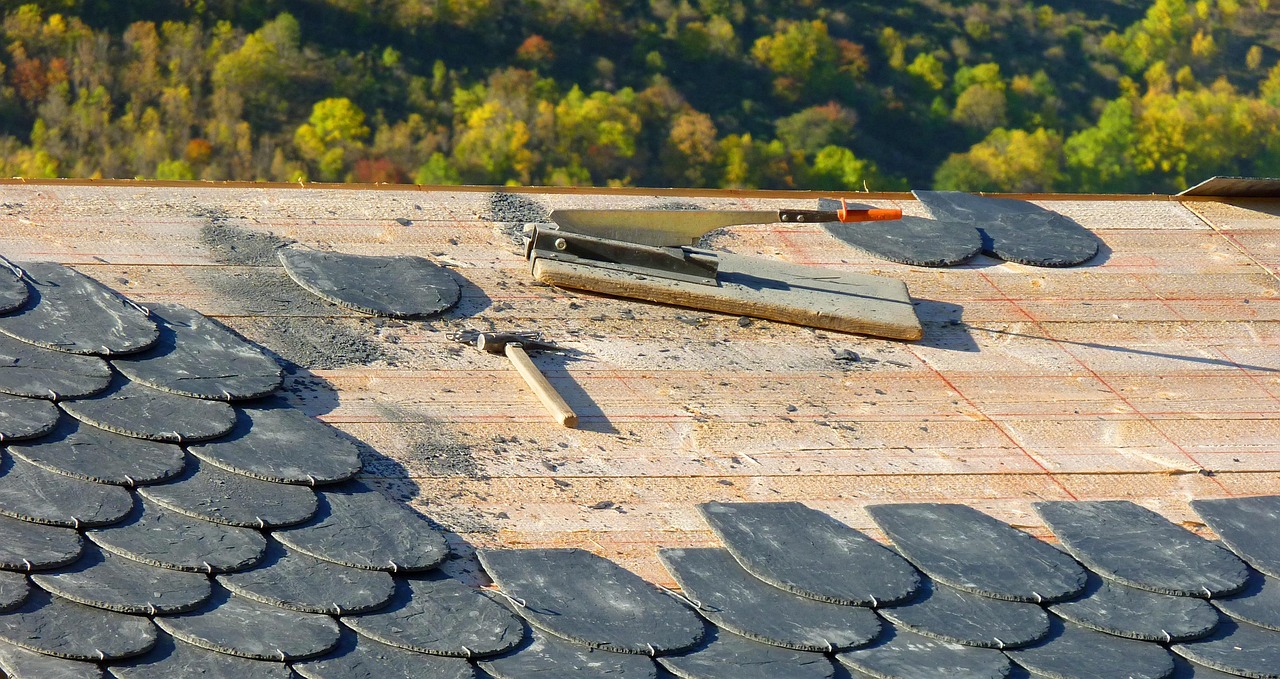
A typical residential roof replacement cost ranges between $8,000 and $18,000 for a standard home, with an average overall cost of about $10,000 for a 1,700-square-foot asphalt shingle installation. Final pricing depends primarily on your roof’s square footage, slope pitch, material choice, and local labor rates in your market.
Replacing a roof is one of the largest structural maintenance expenses you will face as a homeowner. While a basic asphalt shingle tear-off on a simple single-story home can stay under $8,000, multi-story structures with steep slopes, intricate designs, or premium materials like standing seam metal, clay tile, or natural slate easily reach $25,000 to $45,000 or more.
How roof size and surface area affect your total cost
Roofers do not measure a job strictly by the interior square footage of your home. Instead, roofing contractors estimate projects using a measurement unit called a roofing square. One roofing square equals 100 square feet of roof surface area. A 2,000-square-foot single-story home typically has a larger roof surface than 2,000 square feet due to roof overhangs, eaves, and pitch multipliers.
To calculate actual roof surface area, contractors multiply the footprint of your home by a factor determined by roof slope. Here is how estimated total costs scale across common residential roof sizes for basic architectural asphalt shingles:
- 1,000 sq ft roof (10 squares): $3,500 to $6,000 total installed cost.
- 1,500 sq ft roof (15 squares): $5,250 to $9,000 total installed cost.
- 1,700 sq ft roof (17 squares): $6,000 to $9,000 average installed cost.
- 2,000 sq ft roof (20 squares): $7,000 to $12,000 total installed cost.
- 2,500 sq ft roof (25 squares): $8,750 to $15,000 total installed cost.
- 3,000 sq ft roof (30 squares): $10,500 to $18,000 total installed cost.
Comparing roofing material options and installed pricing
The material you choose is the single largest variable in your total project balance. Standard asphalt shingles remain the most common choice due to affordability and ease of installation, but metal, tile, wood, and slate offer significantly longer lifespans at higher upfront price points.
| Roofing Material | Installed Cost per Sq Ft | Expected Lifespan | Best Suited For |
|---|---|---|---|
Asphalt shingles
Asphalt shingles come in three main varieties: traditional 3-tab, architectural (laminated), and high-end designer. Basic 3-tab shingles are lightweight and inexpensive ($3.50 to $5.00 per square foot installed), but they offer less wind resistance and a shorter operational life. Architectural shingles cost $4.50 to $7.00 per square foot installed; they are thicker, handle higher winds, and create a multi-dimensional shadow line that enhances curb appeal. Designer shingles mimic tile or slate and range from $7.00 to $11.00 per square foot.
Metal roofing
Metal options range from exposed-fastener corrugated steel panels to concealed-fastener standing seam systems and stamped metal shingles. Corrugated panels sit at the lower end of metal pricing ($8.00 to $11.00 per square foot installed), while premium standing seam metal systems cost $12.00 to $18.00 per square foot installed. Metal roofs reflect thermal radiation, reducing summer cooling costs, and hold up exceptionally well under heavy snow loads.
Tile roofing
Concrete tiles are more affordable than traditional clay tiles ($10.00 to $18.00 per square foot installed versus $15.00 to $25.00 per square foot for clay). Both materials excel in severe warmth and dry climates, standing up to harsh sun and salt air. However, tile is extremely heavy, weighing between 600 and 1,100 pounds per square. Homes shifting from lightweight asphalt to tile usually require structural framing checks and potential rafter reinforcement before installation.
Wood shakes and slate
Cedar shingles and split shakes provide natural insulation and a classic appearance at $7.00 to $15.00 per square foot installed. They demand routine treatment to resist rot and insects, and local building fire codes may mandate fire-retardant treatments or ban them in wildland-urban interface zones. Natural slate is the longest-lasting material available, frequently outlasting the building framing itself, but commands $15.00 to $40.00 or more per square foot due to specialized stone-masonry labor requirements.
Breakdown of labor and structural tear-off expenses
A typical roofing crew of four to six workers takes one to three days to complete a standard replacement.
Old roof removal and disposal
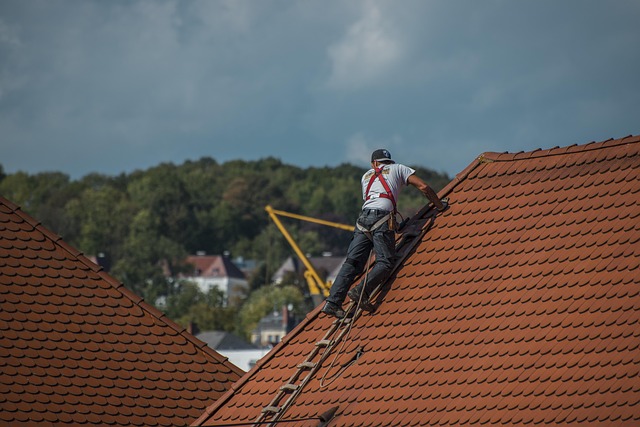
Stripping an old roof down to the wooden deck costs $1.00 to $5.00 per square foot. If your roof has multiple existing shingle layers—a practice previously permitted by building codes—removal costs increase by $1.00 to $2.00 per square foot for each extra layer stripped. Tearing off old materials includes manual labor, chute rental, dumpster fees, and local landfill tipping charges.
Underlayment, drip edges, and flashing
Once the old material is removed, installers lay down synthetic underlayment or felt paper to form a moisture barrier ($0.50 to $1.50 per square foot). In cold regions, installers place self-adhering rubberized membrane (ice and water shield) along the eaves, valleys, and around chimneys to prevent water damage from ice dams. Metal drip edges are installed along roof perimeters, and new aluminum or copper flashing is cut and fitted around sidewalls, dormers, and vent stacks.
Decking repairs and structural plywood replacement
If the wooden roof deck beneath the shingles has suffered water damage or rot, compromised plywood or OSB sheets must be replaced. Roofers typically charge $75 to $120 per 4×8 sheet of plywood replacement, including labor and materials. Until the original shingles are peeled back, contractors cannot guarantee the exact condition of the underlying deck, making framing repairs one of the most common mid-project expense additions.
How pitch, height, and structural design change labor pricing
Roof slope and physical height alter how quickly and safely a roofing crew can operate. Steep slopes slow down production because workers must wear safety harnesses, tie off to anchors, and set up scaffolding or specialized staging equipment.
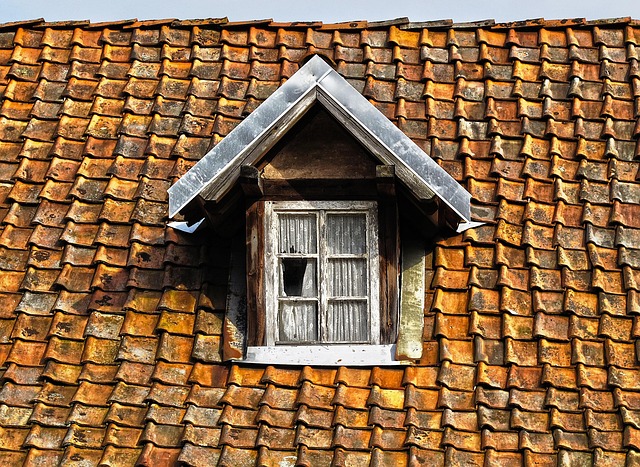
Roof pitch is written as a ratio of vertical rise over 12 inches of horizontal run:
- Low slope (1/12 to 3/12): Requires specialized membrane materials (such as TPO or EPDM) to prevent standing water leaks.
- Standard walkable pitch (4/12 to 6/12): Crews can walk without anchor harnesses, keeping labor rates standard.
- Steep pitch (7/12 to 9/12): Adds 15% to 30% to total labor charges due to restricted mobility and mandatory safety gear.
- Severe pitch (10/12 to 12/12 and above): Can add 35% to 50% or more to labor charges, requiring continuous staging and harness rigging.
Architectural layout affects pricing similarly. A basic dual-sloped gable roof features long continuous surfaces that workers can shingle rapidly with low waste. A complex hip roof with multiple dormers, valley intersections, skylights, and high chimneys requires meticulous hand-cutting and flashing installation.
Hidden expenses to anticipate before work begins
- Permits and municipal inspections: Local city or county building permits range from $150 to $1,000 depending on total project valuation and regional fee tables.
- Skylight replacement or flashing: Old skylight seals often fail when surrounding shingles are disturbed. Re-flashing an existing skylight costs $200 to $400, while replacing a unit entirely during roof replacement costs $800 to $1,800.
- Chimney masonry work: Replacing rotted lead or aluminum chimney step-flashing costs $300 to $700. If the chimney brick requires masonry tuckpointing, repairs can run an extra $500 to $1,500.
- Gutter and downspout replacement: Stripping a roof can damage old or compromised gutters. Installing smooth aluminum gutters simultaneously runs $6 to $14 per linear foot ($1,200 to $2,800 for an average home).
- Attic ventilation improvements: Standard building codes require adequate balanced intake and exhaust ventilation (1 square foot of net free vent area per 300 square feet of attic floor). Adding ridge vents or soffit vents runs $300 to $1,200.
Should you repair or replace your existing roof?
Choosing between spot repairs and full replacement depends on roof age, overall material condition, and the total square footage of existing damage.
When to choose repair
If your roof is under 15 years old and experiencing localized damage—such as a couple of missing shingles after a wind storm, minor flashing uplift around a pipe boot, or localized hail damage—a targeted repair is normally sufficient. Spot repairs typically cost between $300 and $1,200. Repairing makes financial sense when the surrounding shingles remain flexible, hold granular coating, and lie flat.
When to choose full replacement
A full replacement is recommended when your asphalt shingle roof reaches 18 to 20 years of age, or when signs of widespread deck fatigue appear. Indicators including curled shingle edges, bald spots with extensive granule buildup in gutters, soft wooden decking spots underfoot, or interior ceiling stains across multiple rooms indicate systemic system failure. Repeated patch repairs on an aging roof lead to compounding costs without resetting warranty coverage.
Repair versus replacement trade-offs
- Repair Pros: Low immediate out-of-pocket cost, fast turnaround (often a few hours), preserves existing roof material where intact.
- Repair Cons: Mismatched shingle colors due to fading from weather exposure, failure to address hidden rot beneath underlayment, lacks new long-term installer warranties.
- Replacement Pros: Resets entire waterproofing envelope, improves overall energy efficiency, raises property resale appeal, provides comprehensive manufacturer material warranties (25 to 50 years).
- Replacement Cons: Requires substantial capital outlay, creates several days of construction noise and debris.
Financing options to pay for a new roof
Because unexpected roof leaks demand quick resolution, home improvement funding paths are frequently utilized by property owners needing structured repayment options.

- Home Equity Line of Credit (HELOC) or Home Equity Loan: Secured by your property equity, these loans generally offer lower interest rates than credit cards or personal loans. They provide structured terms but carry risk if payments fall behind. Balancing home upgrades within your structured monthly budget helps keep overall debt low; reviewing a practical framework for home renovation savings ensures capital is available before emergency repairs arise.
- Personal loans: Fixed-rate unsecured personal loans do not put your home up as collateral and approve quickly, though interest rates sit higher based on your personal credit score.
- Contractor financing programs: Many large roofing companies partner with third-party lenders to offer promotional zero-interest or deferred-interest plans for 12 to 24 months. Ensure you verify default interest penalties before signing.
- FHA Title I Property Improvement Loans: Government-backed loans offered through approved lenders designed specifically for essential residential structural upkeep, with loan terms up to 20 years.
- Insurance claims: If your roof failure stems from a sudden covered event—such as direct storm hail, severe wind shear, or fallen tree limbs—your homeowners insurance policy may cover the total replacement cost minus your policy deductible. Standard aging, wear and tear, or neglected upkeep are not covered by insurance.
What happens during a roof replacement project?
Knowing the operational sequence helps you verify that your chosen roofing team executes proper waterproofing standards from start to finish.
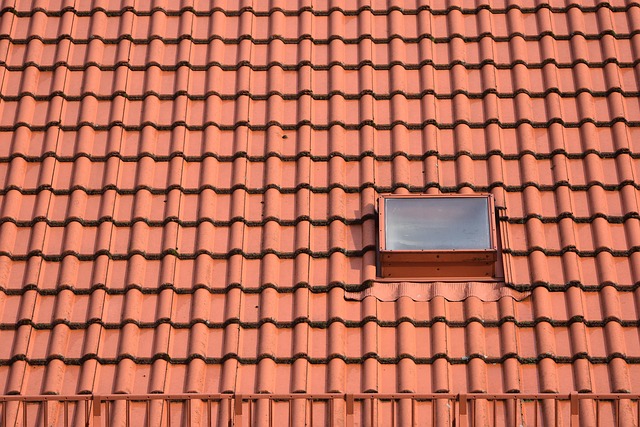
- Contract review and permitting: You sign a scope of work specifying shingle style, warranty parameters, component brands, and payment milestones. The contractor pulls necessary municipal permits.
- Property protection setup: On install day, the crew places plywood shields over air conditioning compressors and hangs tarps from eave lines down to protect landscaping, decks, and windows from falling debris.
- Tear-off and deck evaluation: Installers scrape away old shingles and underlayment down to bare wood. The crew replaces water-damaged decking sheets with fresh OSB or plywood.
- Drip edge and leak barrier installation: Metal drip edge is fastened along lower roof edges. Heavy self-adhering ice and water membrane goes down along eaves, valleys, and wall joins.
- Underlayment and shingle installation: Synthetic underlayment rolls across the entire roof surface. The crew nails down starter shingle strips at perimeter edges, followed by rows of primary shingles using galvanized roofing nails driven to exact depth.
- Flashing, pipe boots, and ridge vents: Installers weave flashing around chimneys and walls, replace rubber pipe boots over plumbing vents, and cut open apex ridge slots to install continuous attic ventilation caps.
- Debris cleanup and final inspection: The crew clears the yard, runs magnetic sweepers across lawn areas and driveways to catch fallen nails, and schedules the municipal building inspector for final clearance.
Costly mistakes to avoid when replacing your roof
Prevent expensive callbacks, voided warranties, and structural premature failure by steering clear of these common pitfalls:
- Choosing the lowest quote automatically: Outlier bids that undercut standard market rates often rely on unbonded casual labor, missing workers’ compensation coverage, or low-tier materials lacking proper manufacturer warranties. Always demand proof of general liability insurance ($1,000,000 minimum) and active local licensing.
- Installing new shingles over an old layer: Overlaying new asphalt shingles over damaged old shingles skips inspecting the underlying wooden deck. It also traps internal heat, shortening new material life by up to 20%, and adds excessive weight to rafters.
- Ignoring attic ventilation requirements: Inadequate airflow traps warm, moist air inside your attic space. This cooks shingles from below in summer and forms internal winter attic frost, rotting structural roof trusses and voiding manufacturer material warranties.
- Reusing old flashing components: Reusing corroded or bent step flashing around chimneys and sidewalls to save a few dollars leads directly to interior wall leaks down the line. Demand fresh metal flashing on every installation.
Sources: Flat roof
Frequently asked questions
How long does a roof replacement take?
Most standard residential roof replacements on single-family homes are completed in one to two business days. Large properties, steep roof slopes, intricate multi-dormer designs, or heavy slate and tile installations can extend work to five days or longer.
Do I need a permit for a new roof?
Yes, municipal building departments require permits for structural roof replacements to verify work complies with local wind resistance and fire safety codes. Reputable contractors include permit acquisition fees inside their initial cost proposal and coordinate required town inspections.
How often should a roof be replaced?
Standard architectural asphalt roofs require replacement every 20 to 25 years. Metal systems typically last 40 to 70 years, while tile and natural slate roofs can endure for 50 to 100 years or more with regular maintenance.
Does a new roof increase home value?
Installing a fresh roof provides strong return on investment, recovering roughly 60% to 70% of project costs in added home equity during resale. It also prevents buyers from demanding steep repair credits during structural house inspections.
What are signs I need a roof replacement?
Key warning signs include curling shingle edges, excessive dark granule accumulation in gutters, sagging wooden rafter lines, water stains on upper-floor ceilings, or daylight showing through attic boards.
Is roof replacement tax deductible?
Replacing a roof on a primary residence is considered a capital improvement rather than a tax deduction, though it adds to your tax basis when selling your property. However, installing qualified energy-efficient metal roofs or integrated solar tiles may make you eligible for federal energy efficiency credits. Consult a tax professional to determine how capital improvements affect your personal tax situation.





Business & Growth
High Yield Checking Accounts: A Smart Money Move
A high yield checking account can transform how your everyday money works for you. Instead of letting your cash sit idle, these accounts offer significantly higher interest rates, allowing you to earn more on your liquid funds.
A high yield checking account is a deposit account that pays interest rates significantly above national averages—often 3.50% to 5.00% APY—while offering full debit, bill-pay, and ATM access. Unlike traditional checking accounts paying near 0.07%, these accounts let your everyday spending cash grow without sacrificing liquidity or lock-in periods.
What is a high yield checking account?
A high yield checking account functions as a hybrid financial tool. It provides the full transactional capability of a traditional bank account—including debit card usage, paper checks, online bill payment, and direct transfers—while yielding interest rates historically associated with long-term savings vehicles. Standard checking accounts at traditional brick-and-mortar financial institutions pay a national average interest rate hovering around 0.07% APY. In contrast, a high yield checking account can return between 3.50% and 5.00% or more on qualifying balances.
The primary appeal of this account type lies in continuous liquidity. While certificates of deposit lock away money for fixed terms and high-yield savings accounts may restrict certain daily transaction routines, high-yield checking accounts are designed for active cash flow. Interest is typically calculated on your average daily balance and credited monthly, allowing everyday operating capital to compound continuously.
Deposits in these accounts receive the same federal protection as standard bank products. Accounts at commercial banks are FDIC-insured up to $250,000 per depositor, while credit union accounts carry identical coverage through the National Credit Union Administration (NCUA). This structure eliminates principal risk while keeping cash accessible for living expenses.
How banks offer high interest rates on checking accounts
Financial institutions do not pay elevated interest rates out of goodwill. Higher APYs stem directly from specific operational models and consumer behavior patterns that drive bank profitability.
Online banks and regional credit unions frequently offer the highest rates because they operate with lower overhead expenses. Without the cost of maintaining physical branch networks, leasing storefronts, and staffing teller counters, online financial institutions pass operational savings back to account holders through enhanced yield structures.
Beyond low overhead, banks use high yield checking to incentivize engagement. When you process a point-of-sale debit transaction, the merchant pays an interchange fee to your card-issuing bank. By requiring a set number of debit card purchases each month, the bank collects enough interchange revenue to offset the cost of paying a high APY. Also, requiring direct deposits ensures a reliable influx of liquidity that the institution can use for overnight lending and reserve requirements. According to financial data tracked by CNBC Select, top high-yield accounts offer APYs ranging from 3.75% to over 5.00% on qualifying balances precisely because these customer activities generate reliable revenue streams.
What requirements are needed to qualify for the maximum APY?
To receive the advertised top-tier interest rate, account holders must meet specific monthly activity benchmarks during each statement cycle. Failing to complete these steps usually drops your earning rate down to a baseline rate, often between 0.01% and 0.05%, for that specific month.
Direct deposit minimums
Most institutions require at least one qualifying direct deposit per statement period, typically totaling between $500 and $1,000. Qualifying direct deposits generally include automated clearing house (ACH) transfers from employers, government benefits, or pension payouts. Peer-to-peer transfers from services like Venmo or PayPal usually do not meet bank definitions for direct deposit.
Debit card transaction counts
Accounts commonly require between 10 and 15 point-of-sale debit transactions per month. To count toward the qualification total, these purchases must settle before the final business day of your statement cycle. Pending transactions that do not fully clear until the following month will not count toward the current cycle’s total.
Digital account management
Banks usually require customers to opt out of paper statements in favor of e-statements. Some institutions also require at least one monthly login to their mobile app or online banking platform to maintain active status.
Balance caps and interest tiers
High yield checking accounts apply their maximum APY up to a defined account limit, known as a balance cap. Common balance caps range from $10,000 to $25,000. Funds held above this threshold earn a lower secondary rate. For example, an account might pay 5.00% APY on the first $15,000 and 0.20% on any balance exceeding $15,000. Some institutions, such as Presidential Bank Advantage Checking noted by Source: WalletHub, cater to higher balances by offering competitive structures on larger balances.
How to choose the right account for your spending habits
Finding the right high yield checking account requires matching bank terms against your existing monthly habits rather than altering your lifestyle to satisfy a bank requirement.
- Evaluate the APY relative to balance caps: Compare the maximum interest rate alongside the dollar threshold. An account paying 5.00% capped at $5,000 generates $250 annually, whereas an account paying 4.00% capped at $25,000 generates up to $1,000 per year. Choose an account whose cap aligns with your regular cash reserves.
- Audit your debit card usage: Review your recent bank statements to see how many times you naturally use a debit card. If you rely primarily on rewards credit cards for daily purchases, meeting a requirement of 15 debit transactions per month may force inconvenient spending adjustments.
- Review ATM access and fee reimbursements: Online institutions rarely maintain widespread physical ATM networks. Verify whether the bank belongs to nationwide networks like Allpoint or MoneyPass, or if they offer monthly out-of-network ATM fee reimbursements (often capped between $10 and $25 per month).
- Check fee structures and waiver rules: Confirm that the account charges no monthly maintenance fees, or that fee waiver requirements are easy to meet. High monthly maintenance fees quickly erase interest gains.
- Examine digital tools and mobile deposit limits: Ensure the bank offers functional mobile check deposits, fast external transfer capabilities, and online bill-pay options to support smooth daily cash flow management.
High yield checking accounts compared to other options
Selecting the proper banking vehicle requires understanding how high yield checking differs from traditional checking accounts and dedicated online savings accounts.
| Feature / Account Type | High-Yield Checking | Traditional Checking | High-Yield Savings |
|---|---|---|---|
| Typical APY Range | 3.50% – 5.00%+ | 0.01% – 0.07% | 4.00% – 5.25%+ |
| Monthly Activity Requirements | Common (Debit uses, direct deposit) | Rare for interest (Common for fee waivers) | Rare |
| Monthly Maintenance Fees | Usually $0 if active | $10 – $15 (Waived with conditions) | Usually $0 |
| ATM & Debit Card Access | Full debit card and ATM privileges | Full debit card and ATM privileges | Limited or no debit card/ATM access |
| Transaction Limits | Unlimited daily transactions | Unlimited daily transactions | May limit withdrawals per month |
| Best Uses | Everyday spending and operational cash | Basic in-person branch services | Dedicated emergency reserves |
High yield checking vs. high yield savings accounts
The primary difference between a high yield checking account and a high yield savings account lies in transactional capability. High yield savings accounts offer competitive APYs with minimal monthly requirements, but they do not provide personal check-writing capabilities or direct point-of-sale debit access. While federal regulations no longer mandate a strict six-withdrawal monthly limit on savings accounts under Regulation D, many financial institutions still impose internal limits or fees on frequent outgoing savings transactions.
High yield checking accounts permit unlimited transactions and provide direct debit card access, making them better suited for everyday expenses. However, savings accounts generally offer high APYs on much larger balances without requiring debit transaction quotas.
Who benefits most from high yield checking?
High yield checking accounts fit specific financial profiles and money management styles.
- Consistent daily debit users: People who regularly make small daily purchases—such as groceries, public transit, or coffee—easily hit 10 to 15 monthly transactions without changing their buying habits.
- Individuals carrying moderate cash buffers: Consumers who maintain between $3,000 and $20,000 in checking to cover upcoming bills earn meaningful passive returns on money that would otherwise earn nothing.
- Savers seeking simplified cash management: Combining earning power and spending access in one place eliminates the need to manually transfer funds back and forth between separate checking and savings accounts throughout the month.
Consider the example of Sarah, a recent graduate who needs her funds accessible for rent and upcoming moving expenses while still wanting to earn interest. Because her job direct-deposits her paycheck and she regularly uses her debit card for daily purchases, she automatically satisfies account requirements, earning yield on her operational cash without locking up funds.
Who should consider alternatives?
High yield checking is not ideal for everyone:
- Credit card rewards optimizers: If you put all expenses on cash-back or travel credit cards to earn 2% to 5% in rewards, switching transactions to a debit card just to satisfy checking requirements can result in a net financial loss.
- Cash-heavy depositors: People who frequently deal in physical cash need access to local branch networks and cash-accepting ATMs, which online high-yield institutions rarely provide.
- High-net-worth liquidity managers: If you hold $50,000 or more in liquid cash, balance caps (e.g., $10,000) mean most of your money will earn standard low rates. Dedicated high-yield savings accounts, money market funds, or short-term Treasury bills offer higher yield across unlimited balances.
Common mistakes that reduce your return
Maximizing the benefits of a high yield checking account requires avoiding operational errors that forfeit interest payouts or incur unnecessary fees.
Assuming pending transactions count
Debit card purchases must completely settle before the final day of your statement cycle. If you make your 15th debit purchase on the last evening of the month, that transaction will likely sit as “pending” until the next cycle, causing you to miss the monthly qualification threshold and lose your top APY for the entire period.
Ignoring the math on credit card rewards
Shifting spending from credit cards to debit cards carries an opportunity cost. For instance, making 15 monthly debit card transactions totaling $1,000 might earn you $35 per month in checking interest. Always calculate the net difference before altering payment habits.
Tax implications on earned interest
Interest earned in a high yield checking account is treated as taxable income by the IRS and state tax authorities. If you earn more than $10 in interest during a calendar year, your financial institution will issue Form 1099-INT. You must report this earnings on your annual income tax return, where it is taxed at your ordinary income rate.
How to integrate high yield checking into your financial system
To maximize financial yield without introducing manual effort, structure your cash flow around an automated deposit and transfer schedule.
- Direct paycheck routing: Set up your employer payroll to route your primary salary directly into the high yield checking account to satisfy the monthly direct deposit requirement automatically.
- Automate fixed bill payments: Configure recurring living expenses—such as rent, mortgage, utilities, and insurance—to draft directly from the high yield checking account. Because your balance earns interest until transactions clear, keeping cash in checking right up to bill due dates maximizes daily interest accrual.
- Establish automated sweep transfers: Monitor your target checking buffer. Once your account balance reaches the maximum high-yield cap (for instance, $15,000), set up an automated monthly transfer to sweep excess funds into a high-yield savings account or investment portfolio. This ensures every dollar earns the highest possible return without sitting idle above tier caps.
Frequently asked questions
Are high yield checking accounts safe?
Yes. High yield checking accounts at banks are insured by the FDIC, and those at credit unions are insured by the NCUA up to $250,000 per depositor. This legal guarantee protects your principal balance against institutional insolvency.
What happens if I miss the requirements for a month?
If you fail to meet monthly criteria like debit card transaction counts or direct deposits, you will not lose your principal balance. Instead, your balance earns the account’s baseline interest rate (typically 0.01% to 0.05%) for that specific statement cycle before resetting the following month.
Is interest from high yield checking accounts taxable?
Yes. Interest earned on bank accounts is taxed as ordinary income. Banks issue Form 1099-INT at the end of the tax year if your account earns $10 or more in interest.
Do high yield checking accounts charge monthly fees?
Most online high yield checking accounts do not charge standard monthly maintenance fees. However, some brick-and-mortar institutions impose fees if minimum balance conditions or monthly deposit rules are not met.
Can I write checks from a high yield checking account?
Yes. High yield checking accounts include full checking features, allowing you to write paper checks, set up online bill pay, and execute direct transfers just like standard checking accounts.
Business & Growth
NerdWallet Careers: Navigating Your Path to FinTech Impact
NerdWallet careers offer a unique opportunity to shape the future of personal finance. This guide explores the company culture, benefits, and how to successfully navigate the application process.

NerdWallet careers offer remote-first positions across software engineering, product management, data analytics, content publishing, and sales, with salaries ranging from $70,000 for entry-level roles to over $150,000 for senior positions. The company operates a consumer finance platform designed to help users compare credit cards, personal loans, mortgages, insurance, and investment tools.
Employees operate within a work environment built on candid communication, continuous learning, and structured remote operations. The company emphasizes direct feedback, independent problem-solving, and documented asynchronous collaboration across time zones.
The rest of this guide outlines NerdWallet’s work culture, specific departmental roles and compensation, employee perks and benefits, and the six-stage application and interview process.
NerdWallet Careers: Roles, Salary Ranges, and Interview Guide
NerdWallet careers offer remote-first positions in software engineering, product management, data analytics, content publishing, and sales, centered on financial clarity and candid collaboration. Candidates undergo a multi-stage hiring process lasting four to eight weeks, with salaries ranging from $70,000 for entry-level roles to over $150,000 for senior positions.
When evaluating a position in financial technology, understanding an organization’s internal workflows, cultural expectations, and interview evaluation criteria dictates success. Working at NerdWallet means contributing to a consumer finance platform that helps users compare credit cards, personal loans, mortgages, insurance, and investment tools. Employees, often called “Nerds,” work within a framework built on transparent communication, continuous professional development, and structured remote operations.
What is it like working at NerdWallet?
NerdWallet operates as a remote-first company, meaning day-to-day operations, project planning, and cross-functional meetings occur primarily online rather than in a centralized physical office. The company adopted this model to expand its talent search across regions and provide flexible scheduling options for staff.
Daily workflow and communication expectations
Because employees work across different time zones, communication relies heavily on structured written documentation and asynchronous collaboration tools. Teammates document decision-making processes in written proposals, shared project boards, and central repositories rather than relying on spontaneous verbal check-ins. Daily tasks require clear self-scheduling, initiative, and disciplined time management. While teams gather occasionally for strategic planning sessions or company events, the default working state remains remote.
Who this work environment suits—and who should avoid it
The remote-first structure works best for self-directed professionals who express ideas clearly in writing and manage their time without daily over-the-shoulder supervision. If you thrive on independent problem-solving and open feedback, you will likely adapt well. However, this environment does not suit everyone. If you rely on daily in-person interaction to stay motivated, prefer strict top-down supervision, or take direct constructive feedback personally, you may struggle within this company structure.
What core values define the company culture?
The workplace culture at NerdWallet emphasizes high performance, constructive feedback, and mutual support across teams. Rather than encouraging internal competition, management focuses on three central cultural pillars.
Candid communication and respectful critique
Employees are expected to speak openly about operational challenges, technical hurdles, and product ideas. In team discussions, staff members challenge assumptions using data and user analytics rather than corporate hierarchy or titles. Providing direct, candid critique in a respectful manner is considered an essential skill, allowing teams to identify flaws in strategy early before products launch.
Intellectual humility and continuous learning
NerdWallet explicitly values staff members who acknowledge what they do not know. Leaders and team members are encouraged to ask questions, admit mistakes, and seek help rather than pretending to possess immediate answers. This commitment to humble inquiry prevents costly missteps and creates an environment where failure is treated as a learning opportunity. It’s a culture where the mission to empower financial decisions drives collective effort.
Diversity, equity, and inclusion initiatives
Diversity, equity, and inclusion (DEI) practices are integrated into hiring strategies, employee resource groups (ERGs), and internal advancement programs. The company uses structured interview rubrics to minimize subconscious bias during candidate evaluation. Active employee resource groups offer community building and professional networking for underrepresented identities, while ongoing internal workshops focus on equitable mentorship and workplace inclusion.
What jobs and departments does NerdWallet hire for?
NerdWallet hires across technical, commercial, creative, and operational departments. Compensation varies based on functional specialization, candidate experience, and role seniority.
Engineering and data science
Software engineers build, scale, and secure web applications, mobile tools, and backend infrastructure that support consumer comparisons across credit cards, loans, and investment products. Data scientists and data engineers build data pipelines, tracking frameworks, and analytical models to personalize user tools. Average base salaries for software engineers range between $130,000 and $150,000 annually, with senior and staff engineers earning higher compensation packages that include equity components.
Product management and UX design
Product managers establish feature roadmaps, define user requirements, and coordinate engineering resources to improve site functionality and conversion rates. Product designers focus on user experience (UX) and interface design, ensuring complex financial calculators and guides remain simple to use. Base salaries for senior product managers often exceed $150,000 depending on product scope and technical complexity.
Editorial, content strategy, and search engine optimization
Content strategists, financial editors, and search engine optimization (SEO) specialists research, draft, and optimize consumer finance guides. Marketers manage organic search traffic, paid acquisition channels, email newsletters, and affiliate partnerships to grow audience reach. Entry-level content and marketing roles start around $70,000 per year, while mid-level and senior specialists earn higher compensation based on channel ownership.
Sales and business development
Account executives, affiliate marketing managers, and business development leads handle commercial relationships with financial institutions, credit card issuers, and mortgage lenders featured on the site. Account executives in mid-market roles earn average base salaries ranging from $80,000 to $96,000, which are typically paired with performance incentive structures.
What perks and benefits do employees receive?
NerdWallet offers a benefits package structured to support long-term physical, financial, and professional well-being.
Health care and personal wellness
- Medical, dental, and vision insurance coverage for employees and eligible dependents.
- Mental health support resources, including access to therapy networks and personal counseling services.
- Family planning support and paid parental leave policies for new parents.
Financial compensation and savings
- Competitive base salaries accompanied by annual performance and compensation reviews.
- 401(k) retirement savings plans featuring company matching contributions.
- Financial wellness tools and direct access to personal financial advisory resources.
Professional development and leave policies
- Generous paid time off (PTO) policies that support work-life balance and rest.
- Dedicated learning budgets covering courses, industry certifications, conferences, and tuition reimbursement.
- Structured internal mentorship programs to help employees move between teams or advance into leadership roles.
How does the application and interview process work?
Applying for positions through NerdWallet careers involves a structured six-stage hiring funnel designed to test technical proficiency, communication skills, and values alignment. The full hiring timeline typically spans four to eight weeks.
- Online application submission: Submit a targeted resume and optional cover letter through the company’s job site. Align your application materials directly with the specific requirements and responsibilities outlined in the job description.
- Recruiter phone screen: Complete a 15- to 30-minute introductory phone interview with a recruiter. This conversation reviews your background, salary expectations, remote work preferences, and interest in consumer finance.
- Hiring manager interview: Meet virtually with the hiring manager to discuss your domain expertise, past project achievements, and experience working in remote or cross-functional team settings.
- Technical or functional assessment: Undergo a skill assessment tailored to your specialty. Engineering candidates take part in live coding challenges or system design reviews. Data analysts complete analytical case studies, while product and marketing candidates present responses to take-home strategy prompts.
- Behavioral and values interview: Complete a structured interview evaluating cultural alignment. Assessors examine how you handle constructive criticism, address project failures, and work collaboratively with others. Prepare concrete examples using the STAR method (Situation, Task, Action, Result).
- Final leadership round: Speak with senior leaders to demonstrate your strategic vision, high-level problem-solving abilities, and overall fit within the company’s long-term operational goals.
How to prepare for NerdWallet interview questions
Interview preparation requires mastering both practical job skills and value-driven behavioral scenario questions. Evaluators look for concrete proof of past achievements rather than broad theoretical assertions.
Structuring behavioral responses using the STAR method
When answering behavioral questions, structure your responses systematically:
- Situation: Describe the specific context, project scope, or operational challenge you faced in a past role.
- Task: State your exact responsibility in resolving the situation.
- Action: Detail the specific steps you took, emphasizing clear communication, technical tools, and collaboration.
- Result: Share measurable results, performance metrics, or key takeaways from the outcome.
Demonstrating candidness and humility
Expect questions asking you to describe a mistake, a project that missed its goal, or a scenario where you lacked technical knowledge. Focus on complete honesty. Describe how you identified the mistake, communicated clearly with your team, sought assistance, adapted your plan, and implemented preventive measures for future work. Blaming former coworkers or denying past mistakes will harm your standing in the interview.
Technical and role-specific preparation
For software engineering positions, review fundamental data structures, algorithmic efficiency, and distributed system design principles. Practice explaining your logic aloud while writing clean code during technical screens. For product and marketing roles, practice breaking down complex user acquisition or feature adoption problems into logical, data-informed decision steps.
What common mistakes cause candidates to fail?
Avoiding standard candidate errors helps you move through the hiring stages cleanly without early disqualification.
- Submitting generic applications: Submitting un-tailored resumes that fail to reference specific role requirements or company goals reduces your chances of passing initial automated and recruiter screens.
- Failing to provide specific interview anecdotes: Giving broad, vague responses during behavioral interviews without using concrete STAR-format examples makes it difficult for evaluators to score your competence.
- Neglecting live technical preparation: Relying solely on past resume credentials without practicing practical coding challenges, system architecture whiteboard sessions, or data analysis case studies often leads to poor technical scores.
- Failing to show strong remote communication skills: Demonstrating disorganized verbal answers or poor written follow-up during interview coordination raises concerns about your ability to work autonomously in a remote-first setting.
Sources: Careers Info
Frequently asked questions
What is the average salary range for NerdWallet positions?
Salaries vary depending on job function and seniority. Entry-level roles start around $70,000 per year, while mid-market account executives earn between $80,000 and $96,000. Software engineering roles generally range from $130,000 to $150,000, with senior positions commanding higher base pay and equity.
Is NerdWallet strictly a remote-first company?
Yes, NerdWallet operates as a remote-first business, allowing employees to perform their work virtually from approved locations. While teams gather occasionally for strategic workshops or corporate events, day-to-day operations are handled online.
How long does the NerdWallet hiring process take?
The recruitment process usually takes four to eight weeks from your initial application submission to a final offer decision. This timeframe covers recruiter screens, technical assessments, behavioral values interviews, and executive interviews.
What benefits and perks does NerdWallet offer?
NerdWallet provides full medical, dental, and vision coverage along with 401(k) matching, mental health support, and financial counseling. Additional perks include generous paid time off, parental leave, and dedicated budgets for professional development and tuition reimbursement.
How can candidates best demonstrate core values in interviews?
Candidates demonstrate values alignment by presenting honest, structured anecdotes using the STAR method. Share real examples of giving or receiving candid feedback, admitting knowledge gaps to learn new skills, and making project decisions that prioritize clear value for the end user.
Business & Growth
How to Start a Savings Plan: Your Blueprint for Financial Momentum
Many people find saving money challenging, but learning how to start a savings plan is the first crucial step towards financial security. This guide offers practical strategies to build an emergency fund, set clear goals, and automate your savings, making it easier to achieve your financial aspirations.
To start a savings plan, track your net income and fixed monthly expenses to determine how much you can set aside, then open a dedicated high-yield account. Automatically transfer a fixed amount or percentage from every paycheck on payday before paying for optional spending, gradually building a three-to-six-month emergency buffer.
Saving money often feels counter-intuitive because human psychology favors immediate gratification over future reward. Spending provides instantaneous feedback, whereas long-term cash accumulation provides security that feels abstract in the short term. This behavioral challenge is reinforced by lifestyle creep, where spending expands to absorb every wage increase or promotion. When income rises, discretionary habits silently upgrade—higher-tier streaming plans, frequent dining out, or upgraded vehicles—leaving net financial reserves unchanged despite higher earnings. Building a durable savings plan requires creating systematic friction that counteracts these natural impulses rather than relying strictly on daily willpower.
How to determine your savings goal and timeline
Before moving money into dedicated accounts, define what each dollar is intended to accomplish. Unallocated cash in a single account easily drifts into general spending. Structuring financial goals into distinct time horizons provides clarity and determines where your money should be stored.
- Short-term goals (under 12 months): Building a $1,000 starter emergency fund, covering annual vehicle registration, funding holiday gifts, or paying for an upcoming vacation. These funds require complete capital safety and maximum liquidity.
- Medium-term goals (1 to 5 years): Accumulating a down payment for a home, purchasing a replacement car without predatory financing, or building a capital reserve to start a business.
- Long-term goals (5 years or longer): Retirement planning, funding children’s post-secondary education, or building wealth through long-term market investments.
Every goal needs a specific dollar target and a fixed deadline. Instead of setting a vague goal to “save money for a home,” establish a clear target like “save $30,000 for a down payment within 36 months.” Specific targets convert abstract ambitions into precise monthly actions—in this case, setting aside $833 per month. The Consumer Financial Protection Bureau notes that setting specific, measurable financial goals significantly increases the likelihood of achieving them compared to informal saving intentions.
Auditing your money flow: calculating actual cash flow
Designing an effective savings plan requires an accurate accounting of incoming cash and outbound expenses. Many people estimate their monthly spending incorrectly because micro-purchases, seasonal bills, and automatic subscriptions escape casual observation.
Audit your financial records by gathering 30 to 90 days of bank statements, credit card records, and digital payment histories. Log every single transaction into a spreadsheet or budgeting app like YNAB without altering your typical spending habits during the audit period. Once logged, separate every expense into two distinct categories:
- Fixed expenses: Mandatory costs with fixed or predictable pricing that recur monthly, such as rent or mortgage payments, insurance premiums, mandatory loan minimums, and utility baselines.
- Variable expenses: Discretionary or fluctuating spending, including groceries, dining out, entertainment, fuel, home decor, and personal shopping.
Subtracting your baseline fixed expenses from your net monthly income establishes your total uncommitted cash flow. This figure represents the maximum monthly allocation available for savings, debt payoff, and discretionary wants. If your initial audit shows spending matching or exceeding total earnings, look for recurring leaks like unused software memberships or redundant entertainment services to free up immediately available capital. (You can also evaluate automated earnings tools; see Rise Early: Beyond Willpower to Sustainable Morning Habits for strategies on earning rewards on daily spending.)
Choosing a budgeting framework that fits your habits
A budget is an allocation plan that assigns every incoming dollar a job before spending occurs. Rather than forcing yourself into a rigid framework that feels restrictive, select a methodology aligned with your mathematical preference and daily routine.
The 50/30/20 budget framework
For example, if your net monthly income is $4,000, the allocation breaks down as follows:
- Needs ($2,000): Rent, minimum utility bills, basic groceries, healthcare, and mandatory debt minimums.
- Wants ($1,200): Restaurant dining, entertainment, hobbies, streaming services, and vacation travel.
- Savings and Debt ($800): Dedicated contributions to an emergency fund, long-term retirement accounts, or extra principal payments on high-interest debt.
Zero-based budgeting
In zero-based budgeting, total income minus total expenses, savings allocations, and debt payments equals zero. Every dollar received is intentionally directed to a specific category or account before the month begins. If money remains unassigned at the end of your planning sheet, allocate it directly toward your priority savings goal.
Pay-yourself-first budgeting
This minimalist framework focuses entirely on your savings rate. The moment your paycheck hits your bank account, fixed savings transfers execute automatically. The remaining balance in your main checking account can be spent on needs and discretionary wants throughout the month without granular category tracking, provided fixed bills remain covered.
Automating your savings with the pay-yourself-first principle
Relying on manual transfers at the end of the month rarely yields consistent results. When savings depend on whatever money remains in checking before payday, discretionary spending naturally expands to consume available balances. Automating your savings removes human friction and decision fatigue from the process.
Establish automated pipelines to execute transfers immediately after income arrives:
- Direct deposit splitting: Instruct your employer’s payroll department or online portal to divide your paycheck into two separate destinations: a fixed percentage or flat dollar amount directly into a dedicated savings account, with the remaining balance deposited into your everyday checking account.
- Automatic bank transfers: If payroll splitting is unavailable, schedule an automated recurring transfer from your primary checking account to your savings account to execute on payday or the morning immediately following.
Automating even modest contributions yields substantial progress over time. Transferring $100 per bi-weekly paycheck automatically accumulates $2,600 over 52 weeks without requiring ongoing manual intervention. Removing daily choices ensures consistent progress toward your savings goals regardless of fluctuating daily willpower.
Where to keep your money: comparing savings vehicles
Storing all savings in a standard checking account or traditional low-yield savings account exposes your cash to inflation erosion and accidental spending. Different financial goals require different account features, balancing annual percentage yield (APY), liquidity, safety, and regulatory protections.
| Account Type | Liquidity / Accessibility | Yield Potential | Risk Level | Best Used For |
|---|---|---|---|---|
| High-Yield Savings Account (HYSA) | High (1-2 day transfer time) | Competitive variable APY | Very Low (FDIC/NCUA insured) | Emergency funds, short-term savings (<2 years) |
| Money Market Account (MMA) | High (includes debit/check access) | Competitive variable APY | Very Low (FDIC/NCUA insured) | Emergency cash needing immediate debit card access |
| Certificate of Deposit (CD) | Low (locked for set term) | Fixed guaranteed APY | Very Low (FDIC/NCUA insured) | Known future purchases with fixed target dates (1-5 years) |
| Traditional Savings Account | Immediate (same-bank transfer) | Near-zero APY | Very Low (FDIC/NCUA insured) | Small secondary buffer attached to main checking |
| Tax-Advantaged Investment (IRA/401k) | Restricted (early withdrawal penalties) | High potential growth via markets | Moderate to High (market risks) | Long-term wealth accumulation and retirement (>5 years) |
High-yield savings accounts provided by insured online financial institutions generally deliver substantially higher returns than traditional brick-and-mortar savings accounts while keeping your cash completely liquid. Certificates of deposit lock money for fixed terms (such as 6, 12, or 24 months) in exchange for a guaranteed interest rate, making them effective for medium-term goals where early access is deliberately discouraged.
Balancing debt payoff while building savings
Determining whether to pay off existing debt or build cash reserves is a fundamental challenge when establishing a financial plan. Carrying high-interest debt while keeping all surplus cash in a low-interest account creates a net mathematical loss.
The solution is a sequenced approach: build a starter emergency buffer of $1,000 to $1,500 first. Two principal debt-reduction strategies exist:
| Feature | Debt Snowball | Debt Avalanche |
|---|---|---|
| Primary Focus | Psychological momentum | Minimizing interest paid |
| Methodology | Pay smallest debt first, then roll payments to next smallest | Pay highest interest rate debt first, then roll payments |
| Psychological Benefit | Quick wins, high motivation | Slower wins, but highly satisfying financial impact |
| Interest Saved | Potentially less overall | Maximizes interest saved over time |
| Best For | Individuals needing motivation to stay on track | Disciplined individuals focused on efficiency |
The Debt Snowball method targets your balance sheet by size, clearing small debts rapidly to create early psychological momentum. The Debt Avalanche method targets interest rates, minimizing lifetime borrowing costs. Choose the framework that fits your personality: if visual progress keeps you committed, use the snowball approach; if mathematical optimization motivates you, adopt the avalanche method.
Common mistakes that derail a savings plan (and how to fix them)
Even well-structured plans encounter obstacles. Recognizing predictable failure points allows you to build preventative safeguards directly into your routine.
Setting overly aggressive targets too quickly
Attempting to double your savings rate overnight by cutting all leisure spending creates friction and burnout. Extreme deprivation routinely triggers rebound spending sprees.
Ignoring irregular or seasonal expenses
Failing to account for non-monthly bills—such as annual auto insurance, vehicle maintenance, property taxes, or holiday shopping—frequently forces people to raid their primary emergency fund. Address this by calculating annual non-monthly expenses, dividing total expected costs by 12, and depositing that monthly fraction into sub-accounts called “sinking funds.”
Co-mingling emergency cash with general checking balances
Leaving savings inside your primary checking account creates an inflated perception of spending power, leading to unintentional depletion. Keep emergency reserves and specific financial goals in separate, dedicated accounts housed at a different financial institution than your daily spending account to introduce physical distance.
Failing to address emotional spending triggers
Impulse purchasing is frequently driven by emotional state, convenience, or promotional advertising rather than genuine functional need. Unsubscribe from marketing communications, remove saved credit card details from browser autofill settings, and mandate a 48-hour cooling-off period before purchasing non-essential items over $50.
Practical strategies to boost your savings rate
Once your baseline automated structure is functioning smoothly, targeted strategies can accelerate your growth rate without straining daily living standards.
- Institute the “found money” rule: Pre-commit to directing 50% to 100% of all unexpected windfalls straight into high-yield savings before spending begins. Applicable sources include annual tax refunds, performance bonuses, cash gifts, side income, or rebate checks.
- Utilize gamified savings challenges: Implement short-term savings challenges to build momentum. The 52-week challenge involves saving $1 in week one, $2 in week two, increasing incrementally up to $52 in week 52, generating $1,378 in cumulative annual savings. Alternatively, run “no-spend weekends” focused exclusively on free local activities.
- Establish an accountability structure: Share your financial goals with a partner or trusted friend who holds similar financial values. Scheduled monthly check-ins provide support and help maintain focus during long savings horizons.
- Connect present choices to your future self: Reframe spending choices from immediate loss to future trade-offs. Asking whether a temporary convenience purchase holds more value than reaching long-term financial independence strengthens daily resolve.
Who a standard savings plan does not suit
While cash accumulation is foundational for financial health, standard liquid savings frameworks are ill-suited for specific financial circumstances:
- Individuals carrying ultra-high-interest loans: If you owe money on payday loans or high-interest cash advances with annual percentage rates exceeding 30%, accumulating excess cash beyond a minimal $500 safety net mathematically erodes wealth. Every available dollar past basic survival must be funneled toward high-interest debt relief.
- Variable gig workers without steady income baselines: Setting up rigid, fixed-dollar monthly transfers can cause accidental overdrafts during low-earning months. Variable income earners require a percentage-based savings system or a buffer-first checking model that adjusts dynamically based on net receipts.
- High-net-worth individuals retaining surplus cash past 12 months: Holding substantial cash reserves beyond 6 to 12 months of living expenses in basic deposit accounts subjects capital to severe purchasing power erosion via inflation. Once full emergency coverage is achieved, excess surplus belongs in diversified investment assets.
Sources: Thrift Savings Plan
Frequently asked questions
How much should I save from each paycheck?
What is the difference between saving and investing?
Saving puts money into low-risk, highly liquid accounts like high-yield bank accounts to protect principal for short- to medium-term goals. Investing places capital into growth assets like stocks, bonds, or real estate to achieve compound long-term gains while accepting market fluctuation.
Can I start a savings plan if I have credit card debt?
Yes, building a starter emergency fund of $1,000 to $1,500 should come first to prevent taking on new credit card debt during unexpected events. Once that initial buffer is established, direct excess monthly cash flow toward paying down high-interest debt balances.
How big should my emergency fund be?
An adequate emergency fund covers three to six months of essential living expenses, including housing, basic food, utilities, and mandatory loan minimums. Single-income households or individuals with variable earnings should aim closer to six to twelve months of basic costs.

Close Your Mind? Why It Actually Holds You Back

Richard Feynman’s Letter to His Wife: A Masterclass

Bird by Bird Anne Lamott: Lessons for Writing and Life

Nurturing Your Areca Palm Chrysalidocarpus: An Expert Guide

White Bird of Paradise: Mastering the Giant Indoor Plant

Drain Cleanout: Your Plumbing System’s Cost-Saving Secret
-
 Home & Living3 months ago
Nurturing Your Areca Palm Chrysalidocarpus: An Expert Guide
-
 Home & Living3 months ago
White Bird of Paradise: Mastering the Giant Indoor Plant
-
 Business & Growth3 months ago
Drain Cleanout: Your Plumbing System’s Cost-Saving Secret
-

 Self-Improvement3 months ago
Beyond Inspiration: Life Is Too Short Quotes & Real Action
-
 Business & Growth3 months ago
Concrete Driveway Cost: Your Essential Budget Guide
-

 Business & Growth3 months ago
Strategic Home Additions: Maximizing Value and Seamless Integration
-
 Home & Living3 months ago
Jacaranda Tree: Cultivating Vibrant Purple Blooms in Your Landscape
-
 Home Improvement3 months ago
Beyond the Tank: Rethinking Septic System Alternatives